You’ve got an offer on your house, or you’re just starting to think about listing and the number that matters isn’t the sale price. It’s what lands in your bank account after the mortgage, the agent commission, and every closing cost gets paid. That number lives on a document called a seller net sheet.
A seller net sheet takes your expected sale price and subtracts everything you’ll owe at closing, so you can see your real payout before you sign anything. This guide walks through what belongs to one, how to calculate net proceeds from a home sale yourself, a full worked example, and a free calculator so you can run your own numbers in minutes.
Try the Seller Net Sheet Calculator
The calculator below does the subtraction for you. Enter your expected sale price, remaining mortgage balance, the commission rate you and your agent agree on, and estimated closing costs, and it returns an estimated net-to-seller figure.
What it needs from you:
- Expected or offered sale price
- Current mortgage payoff amount (call your lender for the exact figure it’s more than just your remaining principal)
- Commission rate (combined, if you’re covering both sides)
- Estimated closing costs as a percentage of sale price
- Any known HOA dues, prorated taxes, or seller concessions
What the result means: The output is an estimate built from the numbers you enter and typical cost ranges not a guarantee. Your actual net proceeds depend on your specific loan payoff, your state’s closing costs and transfer taxes, and whatever you negotiate with the buyer. Treat it as a planning tool, and ask your agent or title company for an updated net sheet once you have a signed offer.
[Calculator widget placeholder] embed the interactive Seller Net Sheet Calculator tool here, positioned directly below this paragraph.
What Is a Seller Net Sheet?
A seller net sheet also called a net sheet for seller, a net-to-seller worksheet, or a seller net proceeds sheet is a line-item estimate of what you’ll actually receive after selling your home. It starts with the sale price and subtracts every cost tied to the transaction: what you still owe your lender, the agent commission, and the various fees collected at closing.
It exists to answer one question before you commit to anything: after everyone gets paid, how much is left for you? That matters whether you’re deciding whether to accept an offer, figuring out your budget for a new home, or simply trying to understand if selling makes financial sense right now.
How a Seller Net Sheet Works
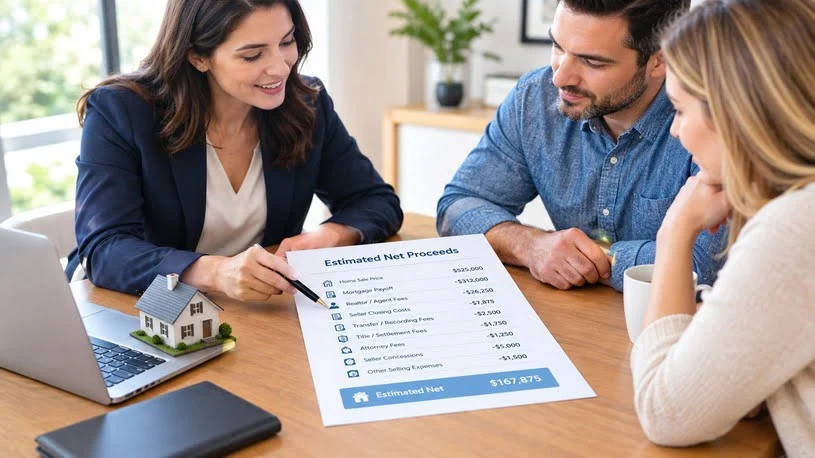
Most sellers get their first net sheet from their listing agent during the initial listing appointment, often alongside a comparative market analysis (CMA) that estimates what the home is likely to sell for. Title and escrow companies can also prepare one, and many publish their own online calculators for a quick estimate.
A net sheet isn’t a standardized, government-issued form; it’s typically a spreadsheet or a simple printed worksheet, and the exact layout varies by agent, brokerage, or title company. Because of that, it’s a good-faith estimate rather than a legally binding document. The final, official numbers show up on the ALTA settlement statement (or closing disclosure) you sign at closing, which is prepared by the title or escrow company handling the transaction.
Expect your net sheet to change more than once. The first version, built around your listing price, is a starting point. Once you have a real offer with its own price, requested credits, and closing date, ask for an updated net sheet that reflects those specific terms.
How to Calculate Net Proceeds From a Home Sale
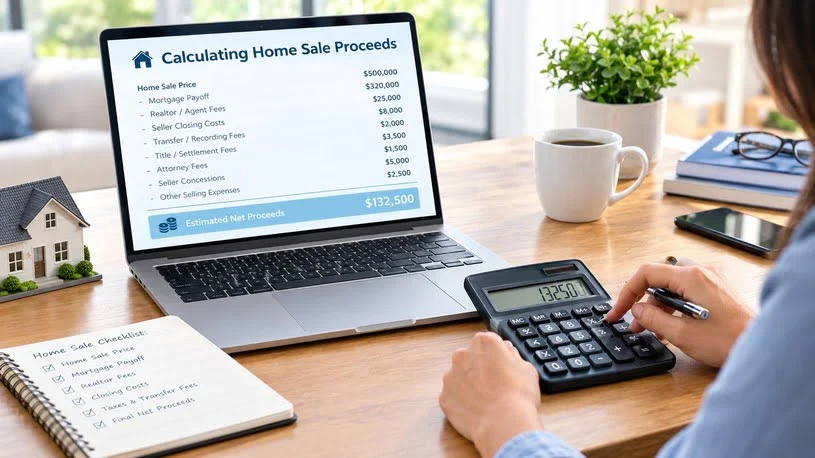
The Net Proceeds Formula
At its core, calculating net proceeds is a subtraction problem:
Net Proceeds = Sale Price − Mortgage Payoff − Agent Commission(s) − Closing Costs − Prorated Taxes & HOA Dues − Seller Concessions ± Other Adjustments
Here’s what each variable means:
- Sale Price the final, agreed-upon price the buyer pays, not your original list price.
- Mortgage Payoff the full amount owed to your lender, including remaining principal, per-diem interest through the closing date, and any escrow shortages. If you have a second mortgage or a HELOC secured against the property, that balance comes off too.
- Agent Commission(s) the fee paid to your listing agent, plus any compensation you’ve agreed to offer or pay toward a buyer’s agent.
- Closing Costs title search and title insurance, escrow or attorney fees, recording fees, and (where applicable) state or county transfer tax.
- Prorated Taxes & HOA Dues your share of property taxes and HOA dues up to the closing date. This can be a credit or a debit depending on whether you’ve already paid ahead.
- Seller Concessions any credits you’ve agreed to give the buyer, such as help with their closing costs or an allowance for repairs.
- Other Adjustments smaller items like a home warranty you’re offering, courier or wire fees, or payoff fees charged by your lender.
Step-by-Step Calculation
- Start with your expected or actual sale price. Use the agreed contract price once you have an accepted offer, not your list price.
- Subtract your mortgage payoff. Request an official payoff statement from your lender; it’s valid only through a specific date and includes daily interest, not just your last statement balance.
- Subtract commission. Multiply the sale price by the commission rate you and your agent have agreed on, and add any buyer’s-agent compensation you’re covering separately.
- Subtract closing costs. Ask your title or escrow company for an estimate based on your state and county; these vary enough that a national average can be misleading.
- Adjust for proportions. Add or subtract your share of property taxes and HOA dues based on your closing date.
- Subtract any negotiated concessions. Include buyer credits, repair allowances, or a home warranty if you’ve agreed to one.
- Total the result. What’s left is your estimated net proceeds, the number that should show up close to (though not necessarily exactly) what you receive at closing.
Seller Net Sheet Example
Here’s a worked example using round, illustrative numbers for a home selling at $450,000 with $210,000 left on the mortgage.
| Line Item | Amount | Running Total |
| Sale Price | $450,000 | $450,000 |
| − Mortgage Payoff | −$210,000 | $240,000 |
| − Agent Commission (5%) | −$22,500 | $217,500 |
| − Closing Costs (title, escrow, transfer tax; ~1.5%) | −$6,750 | $210,750 |
| − Prorated Property Tax Credit to Buyer | −$1,200 | $209,550 |
| − HOA Proration | −$150 | $209,400 |
| − Seller Concession (repair credit) | −$3,000 | $206,400 |
| Estimated Net Proceeds | $206,400 |
This seller walks away with an estimated $206,400 before accounting for their next move or any capital gains tax owed on the sale (see the tax section below). Change the commission rate, payoff balance, or concessions, and the bottom line moves accordingly which is exactly why running your own numbers matters more than any example.
What’s Included on a Seller Net Sheet
| Item | What It Means | Typical Effect on Net Proceeds |
| Mortgage payoff | Remaining principal, accrued interest, and any escrow shortage owed to your lender | Usually the single largest deduction |
| Agent commission | Negotiated fee for your listing agent, plus any buyer’s-agent compensation you agree to offer | Traditionally clustered around 5%–6% combined, though rates are negotiable and vary by market and agreement |
| Title & escrow fees | Title search, owner’s title insurance premium, escrow or attorney fees | Commonly estimated in the 1%–3% range of sale price, but varies significantly by state |
| Transfer tax / documentary stamp tax | A state or county tax charged to record the change of ownership | Ranges from none to a meaningful percentage depending on location |
| Prorated property taxes | Your share of the current tax bill through the closing date | Can be a credit or a debit depending on your local tax cycle |
| HOA dues & transfer fees | Unpaid dues, plus any fee the HOA charges to process the ownership change | Usually a smaller line item, but can add up in HOA-heavy markets |
| Seller concessions | Credits toward the buyer’s closing costs or repairs, negotiated during the offer stage | Directly reduces proceeds; amount is fully negotiable |
| Home warranty | An optional warranty some sellers offer as an incentive | Small, fixed cost if included |
| Recording & miscellaneous fees | Courier, notary, wire transfer, and lender payoff fees | Minor individually, worth listing for accuracy |
What’s Not Included on a Seller Net Sheet
A net sheet estimates your proceeds from the transaction itself it typically does not include:
- Capital gains tax. Any tax owed on your profit is calculated and paid separately at tax time, not withheld at closing in most cases.
- The cost of your next home. Down payment, new mortgage, and moving costs for your next purchase live outside the net sheet.
- Moving and storage expenses. These are personal costs, not transaction costs.
- Pre-listing repairs or staging you already paid for. Those are sunk costs incurred before the sale, not deductions from the sale itself.
- Final walk-through adjustments. Any last-minute repair credits negotiated after the net sheet was prepared won’t appear until the closing disclosure is updated.
Factors That Affect Your Net Proceeds
- Commission negotiation. Since the National Association of REALTORS® settlement took effect in mid-2024, listing agents can no longer advertise a required offer of compensation to buyer’s agents through the MLS. Commission has always been negotiable, but sellers now have more direct say in whether and how much they contribute to a buyer’s agent’s fee. That decision moves your net proceeds up or down more than almost any other line item.
- Remaining loan balance. A second mortgage, HELOC, or recent cash-out refinance increases what comes off the top before you see any proceeds.
- State and local closing costs. Title insurance rates, transfer taxes, and who customarily pays which fee vary by state, sometimes even by county so a net sheet from a different market isn’t a reliable stand-in for your own.
- Buyer-requested concessions. Inspection findings often lead to repair credits or price adjustments that weren’t part of the original offer.
- Timing of closing. Your closing date determines how property taxes and HOA dues get prorated, which can shift the number by hundreds of dollars either way.
Common Mistakes to Avoid
- Assuming your mortgage statement balance is your full payoff. A payoff figure includes per-diem interest and fees your monthly statement doesn’t show.
- Treating 5%–6% commission as fixed. It’s a common range, not a required rate to ask what you and your agent have actually agreed to.
- Forgetting prorated taxes and HOA dues. These are easy to overlook and can meaningfully change your bottom line, especially at certain points in the tax year.
- Skipping buyer concessions in your math. If you’re already anticipating repair requests, build a placeholder into your early estimate.
- Confusing the net sheet estimate with your actual payout. Only the signed closing disclosure or ALTA statement reflects final numbers.
- Ignoring capital gains exposure on a large gain or a non-primary residence. A net sheet won’t warn you if you owe tax on the sale, that’s a separate calculation.
Special Situations
- You owe more than you’ll net. If your mortgage payoff and selling costs exceed your sale price, you’ll need to bring cash to closing or explore a short sale with your lender’s involvement.
- Inherited property. Proceeds calculations still apply, but the property’s cost basis (often “stepped up” to its value at the time you inherited it) changes any capital gains math this deserves its own conversation with a tax professional.
- Divorce sale. Net proceeds are typically split according to your settlement agreement or court order, which may specify a division that differs from a simple 50/50 split.
- Investment or second home. The primary-residence capital gains exclusion (below) doesn’t apply, and depreciation you’ve claimed on a rental property may be subject to recapture get tax guidance before you price the sale.
- Selling without a listing agent (FSBO). You’ll likely skip the listing-side commission, but you may still owe compensation to a buyer’s agent, and title, escrow, and transfer costs still apply in full.
Do You Pay Taxes on Your Home Sale Proceeds?
Your net sheet estimates cash in hand; it isn’t a tax calculation, and the two shouldn’t be confused. Whether you owe tax depends on your gain (sale price minus your cost basis and selling expenses), not your total proceeds.
Most sellers of a primary residence owe nothing in federal capital gains tax, because of the Section 121 exclusion: single filers can exclude up to $250,000 of gain, and married couples filing jointly can exclude up to $500,000, as long as they’ve owned and lived in the home as their main residence for at least two of the five years before the sale. The IRS’s official guidance on selling your home covers the ownership and use tests in detail, along with partial exclusions available for job relocation, health reasons, and other qualifying circumstances.
If your gain exceeds the exclusion or the home wasn’t your primary residence the excess is generally taxed at long-term capital gains rates if you owned it more than a year. Your title company may also file a Form 1099-S reporting the sale to the IRS. Because the math depends on your purchase price, any capital improvements, depreciation (for rental property), and your filing status, this is one part of the net sheet conversation where a CPA’s input is worth the cost, especially on a large or complicated sale.
How to Increase Your Net Proceeds
- Negotiate commission deliberately, not by default. Ask your agent directly what services justify their rate, and whether and how much you want to offer a buyer’s agent.
- Get more than one net sheet. Request estimates from your agent and your title company; small differences in assumed closing costs add up.
- Pay down or clear a HELOC before listing, if you can. Reducing what you owe at payoff has a direct, dollar-for-dollar effect on proceeds.
- Be selective about pre-listing repairs. Spend on the repairs buyers are actually likely to flag in an inspection, not a full cosmetic overhaul.
- Watch your closing date relative to your tax and HOA cycle. Small timing shifts can change how proportions land in your favor.
- Ask for an updated net sheet once you have a real offer. The number built around your list price is a starting estimate; the one built around your actual contract terms is the one to trust.
FAQ
1. What is a seller net sheet? A seller net sheet is an estimate usually prepared by your real estate agent or a title company that shows what you’ll likely take home after selling your home, once the mortgage payoff, agent commission, and closing costs are subtracted from the sale price.
2. How accurate is a seller net sheet? It’s a good-faith estimate, not a final number. Accuracy improves once you have a signed offer, an official mortgage payoff statement, and a title company’s actual closing cost quote instead of estimated percentages.
3. Who prepares a seller’s net sheet? Most often your listing agent, at or before your listing appointment. Title and escrow companies also prepare them, and many offer free online net sheet calculators.
4. What’s the difference between a net sheet and a closing statement? A net sheet is an early, non-binding estimate. The ALTA settlement statement (or closing disclosure) you sign at closing is the final, legally accurate accounting of every dollar in the transaction.
5. Do I have to pay the buyer’s agent’s commission? Not automatically. Since the 2024 NAR settlement took effect, buyer’s agent compensation is negotiated directly between sellers, buyers, and their agents rather than advertised through the MLS. Whether and how much you contribute is a negotiated decision, not a fixed requirement.
6. How do I calculate net proceeds from the sale of my home? Start with your expected sale price and subtract your mortgage payoff, agent commission, closing costs, prorated taxes and HOA dues, and any seller concessions. See the formula and step-by-step breakdown above for the full walkthrough.
7. How much money will I make selling my house? It depends on your sale price, what you still owe on the home, your agreed commission rate, and local closing costs. Use the Seller Net Sheet Calculator above for an estimate based on your own numbers.
8. Do I pay taxes on my home sale proceeds? Most primary-residence sellers owe no federal capital gains tax, thanks to the Section 121 exclusion ($250,000 for single filers, $500,000 for married couples filing jointly). Tax applies only to gain above that exclusion, and investment properties don’t qualify for it. See the IRS’s Topic 701 for the full ownership and use test.
9. Can I get a net sheet before I list my home? Yes most agents and title companies will prepare one during your initial listing conversation, based on an estimated sale price from a comparative market analysis.
10. What if my mortgage payoff is more than my sale price? You’re in a negative-equity position and will need to either bring cash to closing to cover the difference or discuss a short sale with your lender, which requires their approval.
James Anderson is a sales professional focused on helping businesses improve their sales process and achieve better results. He is experienced in using sales tool to manage leads track customer interactions identify opportunities and support business growth. William values clear communication strong customer relationships and efficient sales strategies.